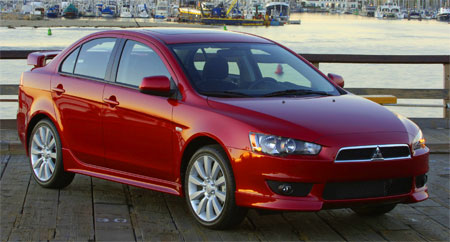
As I promise, here are few shots of the old lady


 this is my house....
As I promise, here are few shots of the old lady
this is my house....
By : Ust Hj Zaharuddin Hj Abd Rahman
(Senior Shariah Compliance Manager, Product Development Division, RHB Islamic Bank Berhad)
One must refrain from making a direct comparison between Islamic banking and conventional banking (apple to apple comparison). This is because they are extremely different in many ways. The key difference is that Islamic Banking is based on Shariah foundation. Thus, all dealing, transaction, business approach, product feature, investment focus, responsibility are derived from the Shariah law, which lead to the significant difference in many part of the operations with as of the conventional.
Another key differentiating factor is the fact that Islamic banking embraces the concept of partnership, profit and risk sharing and value adding between banker (in this case financiers) and client. These elements, when artfully blended and applied will certainly result in a win-win situation in any business.
The foundation of Islamic bank is based on the Islamic faith and must stay within the limits of Islamic Law or the Shariah in all of its actions and deeds. The original meaning of the Arabic word Shariah is 'the way to the source of life' and is now used to refer to legal system in keeping with the code of behaviour called for by the Holly Qur'an (Koran). Amongst the governing principles of an Islamic bank are :
1. The absence of interest-based (riba) transactions;
2. The avoidance of economic activities involving oppression (zulm)
3. The avoidance of economic activities involving speculation (gharar);
4. The introduction of an Islamic tax, zakat;
5. The discouragement of the production of goods and services which contradict the Islamic value (haram)
On the other hand, conventional banking is essentially based on the debtor-creditor relationship between the depositors and the bank on one hand, and between the borrowers and the bank on the other. Interest is considered to be the price of credit, reflecting the opportunity cost of money.
Islamic law considers a loan to be given or taken, free of charge, to meet any contingency. Thus in Islamic Banking, the creditor should not take advantage of the borrower. When money is lent out on the basis of interest, more often that it leads to some kind of injustice. The first Islamic principle underlying for such kind of transactions is “deal not unjustly, and ye shall not be dealt with unjustly” [2:279] which explain why commercial banking in an Islamic framework is not based on the debtor-creditor relationship.
The other principle pertaining to financial transactions in Islam is that there should not be any reward without taking a risk. This principle is applicable to both labor and capital. As no payment is allowed for labor, unless it is applied to work, there is no reward for capital unless it is exposed to business risk.
Thus, financial intermediation in an Islamic framework has been developed on the basis of the above-mentioned principles. Consequently financial relationships in Islam have been participatory in nature.
Lastly, for the interest of the readers, the unique features of the conventional banking and Islamic banking are shown in terms of a box diagram as shown below:-
| Conventional Banks | Islamic Banks |
| 1. The functions and operating modes of conventional banks are based on fully manmade principles. | 1. The functions and operating modes of Islamic banks are based on the principles of Islamic Shariah. |
| 2. The investor is assured of a predetermined rate of interest. | 2. In contrast, it promotes risk sharing between provider of capital (investor) and the user of funds (entrepreneur). |
| 3. It aims at maximizing profit without any restriction. | 3. It also aims at maximizing profit but subject to Shariah restrictions. |
| 4. It does not deal with Zakat. | 4. In the modern Islamic banking system, it has become one of the service-oriented functions of the Islamic banks to be a Zakat Collection Centre and they also pay out their Zakat. |
| 5. Lending money and getting it back with compounding interest is the fundamental function of the conventional banks. | 5. Participation in partnership business is the fundamental function of the Islamic banks. So we have to understand our customer’s business very well. |
| 6. It can charge additional money (penalty and compounded interest) in case of defaulters. | 6. The Islamic banks have no provision to charge any extra money from the defaulters. Only small amount of compensation and these proceeds is given to charity. Rebates are give for early settlement at the Bank’s discretion. |
| 7. Very often it results in the bank’s own interest becoming prominent. It makes no effort to ensure growth with equity. | 7. It gives due importance to the public interest. Its ultimate aim is to ensure growth with equity. |
| 8. For interest-based commercial banks, borrowing from the money market is relatively easier. | 8. For the Islamic banks, it must be based on a Shariah approved underlying transaction. |
| 9. Since income from the advances is fixed, it gives little importance to developing expertise in project appraisal and evaluations. | 9. Since it shares profit and loss, the Islamic banks pay greater attention to developing project appraisal and evaluations. |
| 10. The conventional banks give greater emphasis on credit-worthiness of the clients. | 10. The Islamic banks, on the other hand, give greater emphasis on the viability of the projects. |
| 11. The status of a conventional bank, in relation to its clients, is that of creditor and debtors. | 11. The status of Islamic bank in relation to its clients is that of partners, investors and trader, buyer and seller. |
| 12. A conventional bank has to guarantee all its deposits. | 12. Islamic bank can only guarantee deposits for deposit account, which is based on the principle of al-wadiah, thus the depositors are guaranteed repayment of their funds, however if the account is based on the mudarabah concept, client have to share in a loss position.. |
Salam sejahtera.....
As usual, my day at the office berlalu tanpa aku berbuat ape²....maklumlah, intern jerh....anyway, boss will have to present his proposal paper to upper management on Hicom Perkasa replacement model today....all the best En. Z....
2molo will be my last day at DRB-Hicom....spent 2 months as an intern at the Automotive Distribution Division (ade lima org employees jerh campur I...yet Automotive represent 39% percent of DRB-Hicom business)....gembira sbb pasni bley bgn lambat, holiday....aritu balik jerh terus intern....tp sedeyh arh jgak...sbb dah x dapat keje dlm industri yg i mmg minat...automotive.....
Originally, it was incorporated in 1980 as the The Heavy Industries Corporation of Malaysia Berhad (HICOM). It experienced rapid growth and in 1996 merged with Diversified Resources Berhad (DRB) to form the biggest conglomerate in Malaysia. The conglomerate spans from Automotive manufacturing, Property development and Services.
The Malaysian Government through its investment vehicle; Khazanah Nasional Berhad owns a 10.56% state in the publicly listed DRB-Hicom. Hence it is a blue chip / bellwether stock that plays an important role in the Malaysian economy."
REVENUE: RM3.52billion (2005) EMPLOYEES: 14,689 Suzuki Swift Sport; one of the DRB-Hicom's product. Hope to own this baby one day, but have to find RM104,000 first.
On automotive:
"DRB-HICOM, is one of the prime movers of the automotive industry in Malaysia; being involved in the manufacturing, assembly, distribution and sales of motorcycles, passenger cars, utility vehicles and commercial vehicles. DRB-HICOM's leadership within this sector is reflected through niche segmentation via the development of new and innovative technology applications and continued strategic alliances with renowned global names such as Audi, Honda, Mitsubishi, General Motors, Isuzu, Mahindra, Kawasaki, Suzuki and Tata. DRB-HICOM continuously seeks new alliances to strengthen its base further and develop new business potentials that will strengthen both DRB-HICOM and its partners."
I guess that's it from me today....for all Budu lovers out there (and anyone who want to know what is Budu), go to :--> http://ms.wikipedia.org/wiki/Budu . Babaieberibadi.....
-kaRisu_cHan-

Hello again....
I stumble upon this article while was searching for 'something else'.....a very good read for all Melayu² out there(yg Islam lah...ataupon sesape yg faham BM).....originally from www.zaharuddin.com....baca yg part merah tu...hihi....and sape yg dah baca dan tahu hukum tu....jgn claim tatau atau buat tatau plak....nanti kat akhirat jwb sendiri eik bile ditanya....
Adakah Kad Kredit Haram di Dalam Islam?
Ustaz Zaharuddin Abdul Rahman
Segala puji bagi Allah tuhan sekalian alam, selawat dan salam buat Rasul junjugan Nabi Muhammad SAW, pemimpin para du’at dan Mujahidin yang telah sempurna menyampaikan amanah dan risalah serta memberikan ingatan dan berita baik kepada seluruh manusia. Juga salam ke atas para ahli keluarga Baginda SAW, para sahabatnya yang terpilih serta mujahidin/at dan muslimin/at yang menurut jalan kebenaran Islam.
Penulisan ringkas dan padat ini akan menyentuh aspek berikut :-
1. Pengenalan ringkas jenis Kad Kredit utama yang terpakai di dunia sekarang.
2. Hukum setiap urusniaga dan yang berkaitan dengan Kad Kredit.
Penulisan ini ditujukan khas bagi setiap pengguna kad kredit yang mengambil berat di atas hal -ehwal halal dan haram dalam urusannya dan kepada setiap insan yang ingin menambah maklumat, bagaimanapun penulisan ini dibuat dalam bentuk ringkas, tanpa menuruti kaedah penulisan tesis ilmiah. Ia sekadar suatu bentuk artikel separa ilmiah dituju pada umum dan diharap dapat menjelaskan ‘mawqif’(pendirian) Islam terhadap kontrak yang kian popular di kalangan masyarakat hari ini.
RINGKASAN MAKLUMAT DAN LATAR BELAKANG KAD KREDIT
1. Takrif Kad Kredit
Menurut Kamus Oxford : “ Ia adalah satu kad yang dikeluarkan oleh Bank atau mana-mana pihak lain, yang mana ia memberi kemudahan kepada pemegangnya untuk memperolehi barang-barang keperluannya secara tangguh bayaran (Hutang)”
‘Hutang’ dari sudut syarak menurut takrifan Al-Qadhi Ibn ‘Arabi “Iaitu urusan pemindahan (pertukaran) hak milik (secara jual beli atau seumpama dengannya), yang mana salah satu pihak secara tunai manakala pihak kedua secara tangguh di atas tanggungannya (dengan masa yang ditetapkan atau tidak)”
Manakala Takrifan yang dikeluarkan oleh Ketetapan Majlis Kesatuan Fiqh Islam Sedunia (Majma’ Fiqh Islami) bagi Kad Kredit adalah : “Satu bentuk penyata sandaran (penyata keterangan) yang diiktiraf, diberikan oleh pengeluar kepada mana-mana individu atau pihak yang diiktiraf melalui kontrak diantara kedua-dua belah pihak, ia membolehkan pemegangnya membuat pembelian barangan atau khidmat-khidmat dari semua pihak yang mengiktiraf penyatan sandaran (kad Kredit) tadi, tanpa perlu membuat pembayaran tunai (segara), kerana ia mengandungi jaminan pembayaran dari pihak pengeluar.”
2. Jenis Kad Kredit
Pembahagian jenis Kad Kredit berdasarakan cara-cara pelangsaian bilnya adalah seperti berikut :
a) Kad Kredit Jenis (Charge Card)
Ia adalah kad kredit yang mewajibkan pemegangnya membayar bil penggunaannya setiap bulan.
Antaranya jenisnya : American Express (Hijau), Diners Club.
Antara cirinya yang terpenting :-
1) Tidak disyaratkan pemegangnya membuka Akaun Simpanan di Bank Pengeluar atau Pihak Pengeluar Kad. Juga tidak disyaratkan pemegang mengemukakan apa jua Jaminan Tunai kepada Bank Pengeluar bagi melangsaikan seluruh hutang-hutangnya hasil penggunaan kad.
2) Pemegang kad diberi had tertentu (Credit Line), lalu ia boleh menikmati seluruh hak hutang piutang (bayaran tangguh) dalam satu had ‘tempoh izin tangguh jangka pendek’ yang telah ditentukan, iaitu tempoh antara waktu belian dan waktu wajib langsaian bil. Biasanya dalam 55-60 hari, ketika itu, pemegang akan dibekalkan dengan penyata bulanan yang menyebut transaksi urusniaga yang telah digunakan.
3) Jika pemegang lewat melangsaikan kos penggunaannya dari waktu yang ditetapkan, maka pengeluar akan mengenakan ’penalty’ akibat lewat yang telah ditetapkan di dalam kontrak perjanjian. Mungkin juga akan ditarik balik kad dan dibuang dari keahlian dan sebagainya.
4) Mungkin juga pemegang kad jenis ini perlu membayar yuran permohonan sekali sahaja, dan juga yuran pembaharuan kad tahunan.
b) Kad Kredit Yang Menerima Pembaharuan Bil (Revolving Credit Card)
*Jenis ia adalah yang paling banyak tersebar di seluruh dunia. Antaranya Visa Card, Master Card, Diners Card, American Express Card.
• Ia juga mempunyai banyak ciri yang sama dengan yang pertama tadi cuma terdapat beberapa perbezaan utama.
• Pemegang Kad tidak wajib melangsaikan ‘kos guna’ nya secara keseluruhannya setelah mendapat penyata bil dari pengeluar dalam tempoh izin yang diberikan, TETAPI DIBENARKAN UNTUK MEMBAYAR HANYA NISBAH KECIL DARI BIL . Manakala bakinya, pemegang diberi pilihan samada ingin melangsaikannya dalam tempoh izin yang diberi tersebut ataupun dibiarkan bakinya lalu pihak pengeluar akan mengenakan faedah daripada jumlah bil yang tertangguh ini.
• Kad ini tidak mempunyai had tertinggi penggunaan. Ini bermakna pemegang boleh berbelanja sbanyak mana yang disukainya dan hanya perlu membayar nisbah kecil dari bil, manakala bakinya boleh dibayar secara bertangguh dengan dikenakan peratusan faedah.
• Pemegang Kad boleh menggunakannya samada di dalam ataupun di luar negara di mana-mana sahaja asalkan pihak peniaga mengiktirafnya.
• Ia mempunyai 3 jenis kebiasaannya : Kad emas, Kad Perak dan Kad Biasa.
HUKUM BERKAITAN DENGAN PENGGUNAAN KAD KREDIT
1. Kontrak dan Hubungan Antara Pengeluar, Pemegang dan Peniaga.
Secara amnya, jenis kontrak yang dibuat antara pemegang kad, Pengeluar dan pihak ketiga adalah diktiraf di dalam Islam. Pandangan yang terkuat di dalam hal ini adalah hubungan Al-Kafalah (Jaminan). Dimana ‘Kafil’ (adalah Penjamin-Pengeluar Kad), ‘Makful’ (Yang dijamin- Pemegang Kad) dan ‘Makful lahu’ (Penjual). Semua ini adalah diiktiraf dan kontrak adalah sah di sisi Islam. Kesannya, semua pembelian dibuat dengan kad ini, tiada lagi hak tuntutan pembayaran dari peniaga kepada pemegang kad, kerana ia telah terpindah kepada Pengeluar.
Maka tidak harus peniaga menuntutnya daripada Pemegang Kad. Demikian pandangan Hasan Al-Basri, Ibn Sirin, Ibn Hazm dan Majoriti Fuqaha. Pandangan mereka adalah berdasarkan kefahaman terhadap tiga buah hadith Nabi yang diriwayatakn oleh Abu Daud, Tirmizi, Ahmad, Al-Baihaqi, Ad-Dar Qutni dan lain lain. Justeru tulisan ini tidaklah ingin memanjangkan bicara tentangya.
2. Yuran Penyertaan, Pembaharuan dan Penukaran Kad
Hukumnya : HARUS, tiada masalah dari sudut syarak, ia dianggap sebagai upah yang telah ditetapkan oleh pihak pengeluar terhadap khidmat yang disediakannya. Juga HARUS jika terdapat perbezaan jumlah yuran khidmat bergantung kepada perbezaan jenis khidmat. Tetapi dengan syarat jumlah kos tersebut mestilah setara dengan khidmat sebenar yang diberikan.Jika ia melebihi kos khidmat sebenar, maka ia adalah Riba yang diharamkan.
Demikian keputusan dalam Qarar (ketetapan) dari Majma’ Fiqh Islami (Kesatuan Ulama Fiqh Islam Sedunia) pada persidangannya yang ke-3 , Okt 1986
3. Kos Tertentu Dari Peniaga kepada Bank Pengeluar
Adakalanya pihak Bank pengeluar Kad meletakkan syarat dalam kontraknya dengan para peniaga sejumlah ‘kos tertentu’ dalam bentuk peratusan yang dipotong dari Bil Penjual (Peniaga), yang mana biasanya berlegar sekitar 2-5% atau 8 % dari jumlah Bil. (Lihat Jones , Sally A, The Law Relating to Credit Cards, London, 1989 ,ms 14)
Hasilnya, apabila Peniaga membuat tuntutan kepada Bank Pengeluar, maka Bank akan segera menunaikan bil (Pemegang Kad) iaitu setelah dipotong jumlah kos yang disebut tadi. Kemudian pihak Bank akan menuntut kos asal (tanpa potongan) hasil penggunaan kad daripada pemegang kad.
Hukumnya : Harus . Berdasarkan pendapat mazhab Hanafi yang sah. Jumlah kos ini dikira hadiah kepada Bank pengeluar. (Rujuk Fatawa Hindiyyah, juga Fatawa Al-Bazaziyah, Al-Mabsut dan lain lain ), Terdapat ramai para Fuqaha (Ulama Fiqh) mengganggap ia adalah upah wakil (Ujrah wakalah) kepada Bank kerana menjadi ‘wakil’ bagi Peniaga dalam mempromosikan barangannya serta jaminan wujudnya pelanggan. Ia juga boleh dianggap sebagai Diskaun Khas dari peniaga kepada pengeluar. Ada juga yang mengatakan ia sebagai upah Broker (Ia adalah pandangan Prof. Dr Rafiq Al-Misri).
4. Syarat Mewajibkan Pemegang Kad Membuka Akaun di Bank Pengeluar.
Bagi mereka yang ingin mendapatkan kad, mereka disyaratkan menyimpan sejumlah tertentu di dalam akaun bank pengeluar. Ia sebagai bukti pengiktirafan hak-haknya.
Hukumnya : Harus. Dalam Fiqh Islam, ia mengambil hukum ‘Ar-Rahn’ (Barang Gadaian).
5. Hadiah dan Jaminan Khas Bagi Pemegang Kad Emas (Gold Card)
Ia bertujuan untuk menarik golongan menengah dan atasan bagi menyertai skim mereka. Maka untuk tujuan itu, mereka menawarkan beberapa bentuk hadiah dan skim Insuran Percuma dan Insuran Kemalangan Perjalanan.
Dalam program Hadiah Ahli (Membership Rewards), setiap US dolar hasil penggunaan Kad Emas, pengguna akan mendapat satu mata. Dan mata ini akan bertambah dan jumlah mata terkumpul tertentu akan membolehkan pengguna menikmati program melancong percuma atau penginapan di hotel percuma, atau diskaun di restoran-restoran dan lain lain. (Lihat : American Express Cards, an exclusive opportunity for a select few)
Hukumnya :
1. Hadiah Insuran percuma : Hukum Insuran Konvensional telah diputuskan oleh Sidang Majma Fiqh Islami yang pertama pd 1397 H, sebagai Haram kerana mengandungi unsur Riba,Gharar, Jahalah, Judi dan lain lain. Bagaimanapun dalam konteks ini, hukumnya berlainan kerana pemegang tidak membayar apa-apa kepada syarikat Insuran, oleh itu ia tidak terjebak di dalam hukum haram yang diputuskan, malah ia dianggap sebagai hadiah galakan sahaja dan hukumnya adalah Harus. Ini adalah kerana ia bukannya maksud kontrak tetapi hanya tabi’ (perkara sampingan yang terhasil dari perjanjian). Telah diiktiraf dalam Kaedah Fiqh bahawa (Dimaafkan yang berlaku pada tawabi’ dan tidak pada lainnya- Rujuk Majalah al-Ahkam Al-‘Adliyah).
2. Hadiah-hadiah lain : HARUS atas dasar sumbangan dan derma dan galakan. Asalkan ia tidak terjebak dalam muamalat Bank Konvensional Ribawi. Juga dengan syarat hadiah ini terdiri daripada perkara yang halal di sisi syarak. Bagaimanapun dalam hal seumpama ini ,ulama Mazhab Syafie tidak mengharuskannya atas dasar ‘Sadd az-Zarai’ (Menutup jalan haram dari berlaku).
5. Syarat Menamatkan Kontrak Menurut Kehendak Pengeluar Sahaja
Iaitu pihak pengeluar mempunyai hak untuk menamatkan kontrak walaupun tanpa persetujuan Pemegang kad.
Hukumnya : Syarat ini diterima dan HARUS di sisi Syara’, kerana kontrak yang diikat adalah termasuk dalam bab Kafalah. Ia telahpun dinaskan sebagai kontrak ‘Ghair Lazim’ (Boleh ditamatkan kontrak tanpa persetujuan kedua-dua belah pihak). Terutamanya apabila pemegang kad melanggar perjanjian kontrak.
6. Membeli Emas & Perak dengan Kad Kredit
Majoriti Fuqaha’ (Ulama Fiqh) telah menegaskan bahawa antara syarat sah pembelian emas dan perak dengan wang kertas mestilah transaksi pertukaran berlaku ketika itu juga tanpa sebarang penangguhan, ia disebut ‘at-taqabud fil hal’ dalam istilah Fiqh. Ia adalah berdasarkan Hadith Nabi SAW yang jelas menyatakan perihal tersebut. Wang kertas dianggap dari kalangan harta ribawi (usurious items) dan demikian juga Kad Kredit.
Persoalannya : Adakah peniaga emas dan perak menerima harga bayaran di tempat transaksi jual beli dilakukan?. Dalam hal ini, Fuqaha Semasa menyatakan bahawa ‘At-Taqabud’ sebenarnya telah terlaksana, iaitu dengan cara melalukan kad kredit tersebut di alat bacaan kad kredit ketika pembayaran dibuat. Dengan tindakan ini, semua maklumat telah dihantar ke Bank Pengeluar yang akan menguruskan pembayaran selepas itu.
Maka hukumnya : HARUS dan ‘at-Taqabud’ telah berlaku secara al-Hukmi (secara hukumnya) dan telah tercapai, sebagaimana pembelian dengan cek..Demikian Qarar dan Fatwa dari Majma’ Fiqh Islami dalam sidangnya yang ke 9 pada April 1995 .
7. Pertukaran Matawang (Money Exchange atau ‘As-Sarf’) Dengan Kad Kredit.
Biasanya, pemegang kad boleh menggunakan kad ini di kebanyakan negara di dunia bagi membeli apa jua barang yang dikehendakinya, dengan penggunaan kad ini, maka pihak Bank Pengeluar akan membayar Bil kegunaan di luar negara tadi secara segera dengan matawang negara yang terbabit. Kemudian menuntut dari Pemegang kad dengan Matawang tempatan (dengan menggunakan harga pertukaran hari tersebut - sebagaimana termaktub di dalam perjanjian) bagi membayar bil dalam tempoh izin sekitar 2-3 minggu.
Jelas, terdapat transaksi pertukaran matawang (As-Sarf) dalam hal ini. Sebagaimana maklum syarat dalam Islam bagi pertukaran wang adalah ‘At-Taqabud fil hal’.
Hukumnya : HARAM. Ini adalah kerana kelewatan Bank menerima timbal balik dari pemegang kad, bagi pertukaran matawang yang telah dilakukannya. Bank hanya mendapat timbal tukaran itu selepas 2-3 minggu, ini kerana Bank menuntut Bil dari pemegang kad hanya selepas dikeluarkan bil penyata selain memberinya had tempoh izin. Justeru tiada taqabud haqiqi ataupun hukmi berlaku disini. Lalu Hukumnya adalah HARAM kerana berlaku Riba Buyu’ .
BAGAIMANAPUN dikecualikan dari haram dalam keadaan dharurat dan keperluan yang amat sangat.
8. Denda Kerana Lewat Langsaian Bil bagi ‘Charge Card’.
Terkandung di dalam syarat kontrak bagi ‘Charge Card’, bahawa pemegang kad akan menanggung denda akibat kelewatan melangsaikan bilnya dalam tempoh izin. Sudah tentu ia berbentuk wang.
Hukumnya : HARAM, terdapat unsur Riba An-Nasiah (Riba Hutang) yang sangat dilarang di dalam Islam kerana terdapat unsur menzalimi manusia lain serta memakan harta manusia tanpa haq. Telah Ijma’ seluruh ulama muslim pengharaman riba ini.
Demikian Keputusan hasil persidangan Fiqh bagi Kad Kredit di Bahrain pada Nov 1998. BAGAIMANAPUN terdapat keputusan berbeza dari persidangan AL-BARAKAH ke 12, yang memutuskan HARUS, ia berdasarkan sebab kelemahan kefahaman agama dan kesengajaan dalam melewatkan dalam melangsaikan Bil walaupun mampu. Demikian juga pandangan Syeikh Prof. Mustafa Ahmad Az-Zarqa. Pandangan yang lebih kuat adalah HARAM.
9. Bunga atau Faedah Dikenakan bagi Memperbaharui Bil Bagi Credit Card
Terkandung dalam syarat kontrak ‘Credit Card’ syarat , bagi pemegang yang tidak ingin melangsaikan bil secara sepenuhnya, maka bil yang berbaki tersebut akan dikenakan faedah.
Hukumnya : HARAM, ia adalah Syarat Riba yang dilarang di dalam Islam tanpa sebarang ragu-ragu. Demikian keputusan persidangan Fiqh bagi Kad Kredit di Bahrain pada Nov 1998.
Soalan : Adakah harus seorang muslim memohon Kad ini, yang jelas mensyaratkan faedah bagi bil berbaki?
JAWAPAN : Asalnya adalah HARAM dan batal syarat tersebut. Bagaimanapun terdapat pengecualian apabila ada keperluan mendesak dan tiada pilihan lain, ketika itu hukumnya HARUS, dengan syarat membayar penuh bil tanpa meninggalkan sebarang baki yang boleh dikenakan Faedah.
10. Mengeluarkan Wang dengan Kad Kredit
Ia dianggap pemegang kad membuat pinjaman kepada Bank Pengeluar Kad secara langsung melalui ‘Auto Teller Machine’ bank pengeluar atau cawangannya atau melalui ATM Bank Lain (dikira sebagai wakil).
Hukumnya :
1. HARUS, jika pemegang mempunyai wang yang mencukupi dalam akaunnya. Ketika itu pemegang kad seolah-olah mengeluarkan wangnya sahaja. Jika diambil dari bank lain juga demikian. Dan Harus pihak bank mengambil kos upah dengan kadar khidmat mereka yang sebenar.
2. HARAM JIKA Bank Pengeluar mensyaratkan Faedah atau bunga hasil pinjaman yang diberikan. Kerana ia adalah Riba al-Qurudh. KECUALI JIKA PIHAK BANK PEMBERI PINJAMAN HANYA MENGAMBIL KOS KECIL YANG TETAP, HASIL KHIDMAT PEMPROSESAN YANG DIBUATNYA SAHAJA. KETIKA ITU HARUS , Demikian qarar Majma’ Fiqh Islam Sedunia pada sidangnya ketiga pada 1986 M.
3. Jika Pemegang tiada jumlah yang mencukupi di dalam akaunnya (berlaku overdraft) atau langsung tiada sebarang akaun. Maka dianggap pengeluarannya itu adalah PINJAMANnya terhadap bank. dan semua hukum pinjaman (al-Qardh) di dalam Islam adalah terpakai ketika itu. Sebagaimana Hadith Mawquf : ‘Kullu Qardhi Jarra Naf’an Fahuwa Riba’ Setiap pinjaman yang mensyaratkan sebarang manfaat bagi pihak pemberi pinjaman adalah RIBA.
PENUTUP
Demikian sahaja beberapa bentuk urusniaga yang terhasil dari penggunaan kad kredit. Diharap ianya dapat memberikan gambaran yang jelas terhadap seluruh hukum-hakam yang berkaitan dengannya, dan diberikan kita kekuatan untuk menjauhi mana yang haram sedaya mungkin.
Rujukan :
1. Al-Bidaqah al-Bankiyah, Prof. Dr Abd Wahab Abu Sulaiman, Dar al-Qalam, Dimasqh , cet 1, 1998 m .
2. Qadhaya Fiqhiyyah Mu’asiroh Fil Mal wal iqtisod, Prof. Dr Nazih Kamal Hammad, Dar al-Qalam, Dimasqh, cet 1, 2001 M.
3. Bidaqah al-I’timan min Manzur Islami, Prof. Dr Abd Fatah Idris, Cet 1, 2001 M
4. The Law Relating to Credit Cards, Jones , Sally A , London, 1989
5. Majalah Majma Fiqh Islami , Bil 3 dan 8 , Sidang 1, 3 dan 9
6. Al-Fatawa al-Hindiyyah, cet al-amiriyyah , Bulaq, 1310 H
7. Al-Fatawa al-Bazaziyyah , cet al-amiriyyah , Bulaq, 1310 H
8. Bitoqah al-I’timan, Al-Syeikh Dr Abd Satar Abu Ghuddah
9. Al-Mabsut , Imam As-Sarakhasi, cet as-sa’adah, Mesir, 1324 H
10. Hawl Jawaz Ilzam al-Mumatil bita’wid lid Dain, Majalah Dirasat Iqtisodiyaah Islamiyah, jil 3 , Bil 2, 1996 m.
-kaRisu_cHan-
Hello everybody (if ada org baca blog ni lah).....
Dunno what to post lah today.....dahle pala otak berpusing ligat eih....pening².....memandangkan hari ni tgh bulan Syaaaban....i'll post a Friday sermon by Islamic Religious Council of Singapore on the Nisfu Syaaban topic.....iAllah you guys dpt pengajaran drpdnya....
My brothers in Islam,
I would like to remind my brothers and myself. Let us always have taqwa to Allah s.w.t, and to hasten our taubat, our repentance to Him before death comes to us. For death knows no age, time and place.
Let us grab all the opportunities given to us to be Allah’s pious and obedient servants, who do all that He has commanded, and avoided all that He has forbidden. May by doing that, Allah s.w.t will grant us excellence in this world and the Hereafter, amen.
Maasyiral Muslimin rahimakumullah,
Less than three days away, or this Sunday to be precise, will be the blessed Nisfu Syaaban, the middle of Syaaban. What is so blessed about Nisfu Syaaban?
Today’s khutbah will not only discuss the blessings of Nisfu Syaaban, but its importance in two areas: physical and spiritual.
Let us first discuss its physical importance.
Nisfu Syaaban is a clear indicator that the blessed month of Ramadan is around the corner. One can fast as many as days as one likes before Nisfu Syaaban. But after Nisfu Syaaban, the 15th Syaaban, one should not fast, except for those who are used to fast on certain days, every Mondays and Thursdays for example.
But if one is not used to that pattern, and he wants to fast after Nisfu Syaaban, then it is not advisable for him to do so. In hadith narrated by Imam Ahmad, Rasulullah s.a.w said:
Which means: When Nisfu Syaaban comes, stop fasting until Ramadan.
Since Nisfu Syaaban is a sign to us that Ramadan will be coming shortly, it is well advised that we take that seriously. We should begin our preparations for Ramadan. If we can go to such great extent to prepare beautifying our houses and ourselves for Hari Raya, why can’t we do the same for Ramadan? In fact, Ramadan is more important than Hari Raya. Hari Raya will be celebrated in just one day. Ramadan is celebrated for the whole month and to elevate our spiritual self.
So in all sense, Ramadan is much more important than Hari Raya. Thus, it is important that we make a greater preparation for Ramadan.
Maasyiral Muslimin rahimakumullah,
The blessedness of Nisfu Syaaban lies in its night, which according to our calendar, will fall on this Sunday night.
There are many hadith that conveyed the blessedness of Nisfu Syaaban. Even though a great number of those hadith about the blessedness of Nisfu Syaaban are either weak or dubious, there are many scholars, Ulama, who are of the opinion that, taken as a whole, it indicates that there is some truth on the blessedness of Nisfu Syaaban.
Syeikh Mubarakfuri, a famous hadith scholar of high repute from India, wrote in his book Syarah Sunan Tirmizi, that he supports the blessedness of Nisfu Syaaban. He said that the existence of many hadith, even though weak, seems to convey that there is some truth in those hadith, and that Man does not fabricate them.
But in our earnest to pursue the blessings of Nisfu Syaaban, or any other nights or days for that matter, there are two important things we should remember.
First, we must not dedicate specialized acts of worships for a particular time period, except specified by Al-Quran or authentic hadiths.
Thus for the night of Nisfu Syaaban, we should reject all accounts of special prayers or recitations for that night. There is no special solat for Nisfu Syaaban.
Instead, we should increase our general acts of worship, such as performing sunat prayers, tahajud prayers, reciting Al-Quran, remembering Allah through zikir, and to seek his forgiveness.
The second thing that we should remember is that: when we perform any acts or worship, we should not do them purely for the sake of receiving its promised rewards.
For example, it has been promised by our Prophet Muhammad s.a.w that whosoever fast six days after Ramadan, will be rewarded as if he has fasted for the whole year. While this promise can be regarded as an encouragement and motivation for us to perform such act of worship, it should not be the only reason for us to perform that worship.
Instead, we should be sincere when worshiping Allah. Not for this reward or that reward. For sincerity is its best reward.
When someone is sincere in worshiping Allah, he will receive unlimited rewards. Rewards that only Allah knows. Allah says in surah Al-Baiyyinah, verse 5:
Which means: And they have been commanded no more than this: To worship Allah, offering Him sincere devotion, being true (in faith); to establish regular prayer; and to practise regular charity; and that is the Religion Right and Straight.
My brothers in Islam,
Let us not just regard Nisfu Syaaban as a sign that Ramadan is near. We should also regard Nisfu Syaaban as a sign that we should look into ourselves, to do some self-accounting on our past deeds. How little our devotions to Allah are and how much our sins are. How unprepared we are for the blessings of Allah in Ramadan.
If that is our condition, we should seriously consider doing some house cleaning. Not for our physical houses, but for our hearts, and our spiritual self. Grab the opportunity presented to us in the night of Nisfu Syaaban to repent on all our mistakes, and to seek forgiveness from Allah. And for two weeks after that, let us watch carefully our character, our manners, so that when Ramadan comes, we will be spiritually ready for it.
Besides doing self-accounting on ourselves, let us also do self-accounting on our community, and the Ummah in general. Ramadan comes. Ramadan goes. Has there been any improvement in our community? Are there members of our community who still disregard, or worse, do not respect Ramadan?If there are, then we should do something. We should use self-accounting as a tool to take stock of our community and ourselves.
Let us be aware of the mistakes and deficiencies, and then take steps to correct and overcome them.
This is a characteristic of an excellent society, to constantly do self-correction and tackle problems head on.
We Muslims are special. If other communities do self-improvement for their life in this world, we should do more. We are commanded to improve both our worldly life and our life in the Hereafter. We should be a model and inspiration to all.
May the coming days witness a positive change in our community, and ourselves amen.
To those yg berpuasa, selamat berbuka puasa......byk2kanlah pose time bln Syaaban ni eik....Rasulullah s.a.w. pon byk pose time bln eih (except Ramadan arh...yg tu full one month).....babai =p
Baru ku tahu bahawa sebenarnye wujud lagi satu variant 190e....AMG 190e 3.2l...more about it at http://www.geocities.com/shvoldum/conversions/AMG32.html And a crazy Norwegian modded his 190e to produce 450bhp!!!! ---> http://www.geocities.com/shvoldum/conversions/cosworth.html
Bacalh...jgn malu² =)

I'll start my post this year (hihihi...dah bulan 8 dah weih) with my father pny project.....mahu bikin Mercedes 190e yg dah lama tersadai kat umah...the merc oledi berusia 21 yrs old (1986 model)....abah don't want to sell it because he said byk sentimental value...plus, is the only merc we can afford...hihi....up till now i think about RM10k already spent on engine repairs, servis aircond, new 17" wheels set (although rims just replica not ori amg, but still Made in Germany!...tayar Firenza - Japan mari...but lupe plak what series).....oledi change to new adjustable cambers.....
The car is still using APEX racing springs with Bilstein absorbers....lowered meh, baru nampak cun....nothing done to the engine...still using the stock 2.0litre one...oledi got more than 400K mileage....but still going strong, cruising at 150km/h smoothly and capable of reaching 180km/h (just test drive wif my abah couple of days ago)....but abah oledi bought Denso iridium spark plugs....next time send the car to workshop going to 'install' it...he olso talk bout repaint the old lady into Black....and changing all the lights to clear glass one(Taiwan mari,...hihi)....but I told him better to find AMG or Cosworth half-cut and do engine swap.....I want more power. For the engine transplant, if possible swap the 2.0l with the 2.3l twin-cam 16v cosworth engine.....ther's this one fella in Klang selling it for RM7k....some fact on the engine & its reputation:
1. European Sedan Series Champ- 83, 84, 85, 86
Sedan Series Racing is Europe’s equivalent to NASCAR. Mercedes successfully teamed up with AMG and other aftermarket sources to create a competition 190 Sedan. Aarton Senna, Alan Probst, and other up-start F-1 drivers were employed. Senna, often considered the most talented driver in history, took the series championship in 1983 at the wheel of a 190E 2.3-16.
2. 2.3 Liter Four cylinder sixteen-valve “twin-cam” engine- 167 hp, rev limited to 6,800 rpm
3. Five speed close ratio transmission. (1:1 in 5th gear)
4. Limited Slip rear axle with 3.64:1 ratio
5. Endurance Speed Record Holder- 154.06mph for 50,000 km
Endurance Records were set in August of 1983 at Nardo, Italy’s 12.6- km oval. A team of drivers and crew fielded three identical 190E 2.3-16’s, which covered 50,000 km in 201 hours. Including fuel and maintenance stops the cars averaged 154mph. The engine literally ran at 6,000 rpm for eight days around the clock.
Haha.....i want to inject some racing dna into the old lady and boost it pedigree....Car & Driver (a well-known automag in case u dunno) actually tested and drive it on the Autobahn and managed to achieve the speed of more than 160mph...!
The 190e also come in variants of 1.8l, 2.5l 16v and 2.6l. Hopefully this dream (daydreaming!!!) will come true....then i can drive the old lady with pride...hehehee....will post the pcis of the old lady in later post...rite now, i want a DSLR camera...mau blaja photgraphy....
if want to know more on the W201 history+stuffs....got to ---> http://en.wikipedia.org/wiki/Mercedes-Benz_W201
ciao!
huhuhuhu...ini blog lama sudah takde post....iAllah kami akan menghidupkannya kembali....jom suyung...start posting!!!


 Saya sayang ibu saya
I’ve been wanting to write about this very ‘bothering’ matter a long time a ago.. It’s just today that my spirit is lifted and yeah.. I’m going to write about this profit making strategy my lecturers just adopted…
This is a totaly unrelated subject but let me started with the tuition fees, us, international students got to pay.. for me its 8000++ pounds and it can be more than 11000 for those who chose Warwick.. Since I am paying like 7 times more than the locals, I should be entitled to a few privileges, if not dozens, right? Wrong.. but its not the thing I’m very much concern about now, although I DID experienced an immature guy (who I suspected IS a student and paying a lot less that I am) screaming and swearing at me out of nowhere for some unknown reasons (or could it be the head scarf I was wearing?) anyway, let’s ignore that since I’m not paying using my money..
Well anyway, in my first econs lecture, my lecturer made me lega a little bit by bringing in the news that they had written a custom textbook that would cover everything, yes, everything in the course.. Of course I innocently had expected that it would be sold at reasonable price.. So, as September, October, November and December passed by, the text book was no where to be seen. The blame was of course on the publisher..(Pearson if I’m not mistaken).. After I’d given up much hope for that book to be ready before I finished my first year, it was finally available at Blackweir. It would be stupid if I buy something without checking first rite? So, as I flipped thru the book, to my surprise, it is made up of pages and pages of Mr Sloman’s. Except they are in black and white, as opposed to the colourful ones in the original.. So, what did I do? I bought a brand new Sloman at a bargain price straight away.. no need to think twice.. Besides, I’ve always love Sloman. In the mean time, the lecturer, keep on reminding us ( or could it be persuading? Or commanding? Or threatening?( to the extreme ) ) to buy the book.. Wait, I haven’t clearly stated what the book’s got rite? Right, other than those photocopied pages of Sloman, it has lecture notes, tutorial questions, stuff that my lecturers wrote ( which isn’t that many, don’t be fooled ppl..) and also a small part from another book which my lecturer claimed no longer available in the market and cant be found in the library.. (but then again, since its just a few pages why cant they just fotostat those like Mr Jamal did?) Since I just bought a new Sloman, I asked my lecturer, do I still need the book.. And he asked whether I bought it at the uni book store. As I said no, he said, would they know?.. Just in case you haven’t figure it out yet, he was simply suggesting me to tukar the book (which I bought from somewhere else) with the custom text book at the uni book store, pretending that I bought it there, of course. It’s such a brilliant idea wasn’t it? (yeah, I would consider that should the ‘suitable’ situation arises..) I would like to believe that’s normal except the fact that it is morally incorrect.. What really pissed me off is that, with the existence of the text book, we are no longer given lecture notes and the slides are no longer uploaded to Blackboard. So these days, I go to class and copy the lecture slides + the verbal lectures + the graphs, which is very tiring.. The reason we are no longer supplied with notes is just to force us to buy the text book.. This is such a taktik kotor isn’t it?.. Believe me, at 40 pounds, the text book is wayyyy overpriced.. Come on.. I mean, since when do we have to pay for lecture slides?.. isnt that what tution fees are for? Believe me, they really want us to believe that we are going to fail if we don’t have the text book.. I tell myself, I’m not going to fall into this trap.. I really don’t want to think that both my lecturers are selfish with only royalties in mind.. I try to understand their situation, surely they have to make sure that the sales of the books go well. If not, they’d surely be blamed by the publishers, rite.. But anyway, the fact that I HAVE to copy everything down and not given other option but to buy that pricey text book is totally unacceptable..
Well.. its true that I am being kedekut here.. but my kedekutness is well justified rite? I won't breathe a word if the book is totaly a brand-new-out-of nowhere stuff and not photocopied copies of others + supposedly free notes.. I DID buy that Sloman book rite? and I DID consider buying a new Glen Arnold's which costs about 40 pounds ( and I am still considering it now..)
Anyway sayang, just a friendly reminder (hahhaahhhah…) don’t forget your promises ye.. --watch your diet.. If watching alone is not enough, then try restricted diet instead.. Everything being said, love you whether you are bulat or not..
Hello!!
It’s been quite a while since I last updated my blog.. Nothing much really happened, I have so many things to watch.. I have movies and dramas lining up and honestly I really dont know when I’ll finish watching them all.. Its not that I’m busy or anything, It’s just me being me, me being purely malas.. The drama that I’m watching now is Devil Beside You (Mike He and Rainie Yang).. A couple of frens said this drama is good, so I was soo bersemangat to watch.. Besides, this drama is so popular and got very good reviews, and also originated from a manga.. So my expectation was kinda high.. However, it turned out to be that it’s just the normal (or should I mention ‘stupid’) Taiwanese drama.. Taiwanese dramas always have this reputation of being crappy, and this Devil Beside You really proves that they just HAVE to be stupid.. Really, you cant expect much from them.. Except, of course, the very outstanding Mars. The performance of Vic Zhou has improved a lot since Meteor Garden and Barbie Hsu suits the role perfectly. They really have chemistry between them and someone said, ‘with all those saucy scenes, no wonder they fall for each other’.. I really cant comment on this since I haven’t finished watching them.. I have all the episodes but cant find the subtitles anywhere.. So now, I just put up with it although inside I’m burning with anger.. hahhahhaha… However, the credits don’t all go to the production team since it’s originated from a manga.. Soon, these Taiwanese producers will be running out mangas and they might come out with er.. Sailormoon perhaps?...
Well, I just completed my collection of the shophaholic series today and I am soooo happy.. I really couldn’t believe that all it took was to jalan2 at Albany Road.. I love Becky to the max and really cant accept the fact that there’s no more of the series to be written.. Not only I love the series, I also love the writer. So now, my ultimate goal and the only hers left on my list is ‘The Undomestic Goddess’. Here is the photo of my most prized possessions… Shophaholic Abroad (or Shophaholic Takes Manhattan) is not in there.. But yeah.. I read that alredi..


Warwick M-Nite is today (19 hours and counting) .. I am wishing Khalis the best. Yeah sayang, I know you can do it.. Being a technical director for an event as big as that isn’t easy and I’m sooo hepi that you are doing very very very well.. I have no doubt everything will turn out OK and I’m so proud that you are contributing A LOT.. Your effort and time (and blood and tears and the demam yg teruk) spent aren’t mean nothing.. You know you are doing the best (and you are the best anyway) you deserve this BIG applause…
Clap!! Clap!! Clap!! Clap!!.
Just calm down, and bertahan a little bit more.. Its gonna be over very very very soon..
Love you so much and I’m waiting for the good news...
Just dont go fainting k..
kaRiSu_cHaN:
This post is dedicated to myself who are now suffering from cold....or is it flu????Whatever....it doesn't feel nice at all.....let us see some facts....
And now....my life depends on one medicine....the infamous Lemsip Max...
Hope I will get better as quickly as possible....I can't stand it anymore.....
HayyaMnyra:
Hello…!!
I’m going to Warwick tomorrow…yay!! so hepi!!
Khalis forced me to take the earliest possible train so maybe I’ll take the 845 one.. waaaa….so early… It means that I have to wake up paling lambat 730 and start walking at 8.. Encik Khalis..you sooooooo have to treat me good.. This is a huge+great+big pengorbanan of mine since my normal bgn tido time is 11…(oppsss..before you guys start labelling me pemalas, I sleep around 3 everynite tau..)
Yesterday was my birthday..Khalis forgot to wish on time and I took it as a bad sign.. It’s only my third birthday with him and he already lupa.. Surely I’d understand if this is my 50th birthday with him..
Omigod!!! I’m soo old.. I wish I’d stay 18 forever.. My housemates said “WOW!!” when they knew I’m already 21..but for me, the fact that I’m now 21 is really depressing.. I always have this famous pepatah arab in mind –masa ibarat pedang.. It is so true.. Every new day that arrives keep on reminding me of the useless days I’ve been living for the past 21 years.. There are things that can never be corrected and things I’d never get the chance to do.. My life can never be perfected and before I know, I will become old and berkedut2… there’s no way I can escape that so sayang, let’s grow old together and cheer me up when I cry bcoz of my kedut2.. Now I’m size 8-10 and be prepared for the day I’ll be wearing 18…
But anyway, it’s one of the best birthdays I’ve had.. a lot of people remembered and I got byk cards.. there was no birthday party but masak lemak udang my fren cooked was sooo sedap..(although it wasn’t actually for my birthday…ahahhahhah)
My water heating system got rosak for a few days and I mandi with air yg sejuk giler cam air batu.. Different people came everyday to fix it and its only today the problem could be identified… Finally..
So Warwick.. I’m coming…
kaRisU_cHaN:
Sayang.....hepi burfday....sowi coz terlupa wish time 12 o'clock....already put the reminder and asked u earlier when u r going to sleep...but somehow forgot to call....ampun!!!~~~.....got high watching movie....Leon, The Professional (1994)....great movie....

| Cast overview, first billed only: | ||
| Jean Reno | .... | Leon |
| Gary Oldman | .... | Stansfield |
| Natalie Portman | .... | Mathilda |
| Danny Aiello | .... | Tony |
| Peter Appel | .... | Malky |
| Willi One Blood | .... | Stansfield Man #1, Willi Blood |
| Don Creech | .... | Stansfield Man #2 |
| Keith A. Glascoe | .... | Stansfield Man #3, Benny |
| Randolph Scott | .... | Stansfield Man #4 |
| Michael Badalucco | .... | Mathilda's Father |
| Ellen Greene | .... | Mathilda's Mother |
| Elizabeth Regen | .... | Mathilda's Sister |
| Carl J. Matusovich | .... | Mathilda's Brother |
| Frank Senger | .... | Fatman |
| Lucius Wyatt Cherokee | .... | Tonto (as Lucius Wyatt 'Cherokee') |
Hype!!!
I went to the city today for the sales my friends had been raving on and onnn… just what I had expected, I ended up buying nothing..yep..nothing at all.. There were of course good+cheap stuff but my (or we, girls) main problems are:
1. The pants were all too long.
2. NO size 8.. or maybe I got there a bit late..
3. Reductions were only on skimpy clothes.
So, to get rid of the frustration, I spent hours on E-bay and bid for baju2 like crazy..
Khalis always said that I'm too kedekut and wont but anything that's a little bit pricey,well... let me clarify then..
Question:
Why did I go to the city?
Answer:
Because there are sales going on (which means prices are expected to be low).
Since the keyword here is SALES (or "buy one get one free" as Dorothy Perkins put it), it will be totally waste of time and effort (and money oso) for me to buy the stuff on reductions, but still reflecting the normal prices.. If I'm going to buy things at normal prices, then why do I have to wait for sales? I can just point my finger on any date and go shopping anytime anywhere.. Get what I mean? I dunno...ahahhahahah...
Okehs.. the second drama that I finished is Kimi Wa Petto (You’re My Pet).. Matsumoto Jun’s there again..and this time he’s a lot better. He’s sooo kawai in Kimi Wa Petto. It’s like the role’s tailor-made for him. I’d seen him being serious in few dramas and I found it very klaka+tak seswaiiiiiiiii .. So, the story is about this guy, Takeshi, who got beaten up and hid himself in a big box. He is found by Sumire Iwaya (she’s cold blooded, hated by many and just got dumped by his bf) who later fixes his cuts and bruises. She then leaves a note for him to eat some food she made then go home because she had to go to work. When she gets home however she finds that he is still there. He tells her that he wants to live there with her like a brother or cousin. In desperation to get him to leave she tells him that if he became her pet then he could stay. And as a pet she says that he would have no rights and do whatever she told him. (not in that perverted way!) To her surprise he agrees and from then on he is known as Momo, her pet. Oh, btw in this drama, she’s 29 and he’s 20.. wait, before you say "yucks", watch this drama and you'll agree with me that they look good together..
(note:this is partly cut & paste from a website)
I stay up until 6 am to watch this. Since I suka gila tido, this drama must be very good that it kept me awake all nite rite?
Matsumoto Jun as A Pet (Goda Takeshi)
Strong, icy woman (Sumire Iwaya)
Encik Khalis, stop being malas and skipping classes..esok pg kelas ye...
kaRisU_cHaN:
aiyoyo....I just can't stop eating....last nite before sleep just habiskan a kilogram of grape, tiramisu, choux bun with choc sauce, and a packet of cheese & onion hula hoop....me going to explode...=(
today also malas pg lecture econs....jauh arh westwood....to make it more interesting....i don't even attended any lecture this week (up to this day arh....)....tomorrow friday of course larh more malas....die...die...die....
in addition....essay, presentation, hutang library....flight tickets still tak settle yet.....wake up Karisu -chan!!!!!!
Tiramisu: Heaven in your mouth!!!
Hello!!!
I just finished my second paper which was considerably hard.. It never occurred to me that opportunity cost could be so confusing..( it’s the first thing we learnt in econs after all..)..but anyway... I’m soooo hepi that all my worries are now gone.. I only have maths left but I’m not worried lansung..
So..these 2 weeks,as I said before, I’m so busy watching drama.. The first that I finished was Hana Yori Dango.. I am a huge fan of Meteor Garden and although this one can be considered as a remake, they are different. There are of course similar scenes and dialogue, but Hana Yori Dango is Hana Yori Dango. So, its not Meteor Garden at all. While in Meteor Garden emotion is running high, Hana Yori Dango however is a hepi2 teen drama.. since i've watched Meteor Garden like beribu2 kali already, it has gradually became plain and tak best..(well..at least to me..)..Btw, during the period that I was crazy bout Meteor Garden, I once refused a family vacation bcoz i didn't want to miss it on tv..
I wasn’t interested at all to tgk Hana Yori Dango before ,simply because Matsumoto Jun is sooooo buruk in it.. I must say that Jerry Yan did much much much better.. Jun's acting is also bad (especially the unnecessary tears when Rui's leaving), but anyway, he’s very very popular+hot now rite?
A lot of people watched Hana Yori Dango already..so there’s no need for me to do reviews. I had great time watching Hana Yori Dango and so if you guys got the chance, don’t hesitate, just watch it.. I’m not saying that its not boring (yes, it is a little bit).. but seronok jugak arhh..
So here I just upload the gambars of the few pelakon2.. they look nice don’t they?
Especially Sada Mayumi.. (she’s Rui’s (or Hua Zhe Lei) lover btw..)..
Matsumoto Jun (Domyouji Tsukasa)
Mayumi Sada(Toudou Shizuka)
Inoue Mao(Makino Tsukushi)
Oguri Shun (Hanazawa Rui)
To Khalis dearie..jgn makan byk, your Weight and Health Risks Assessment result is worrying tau..